
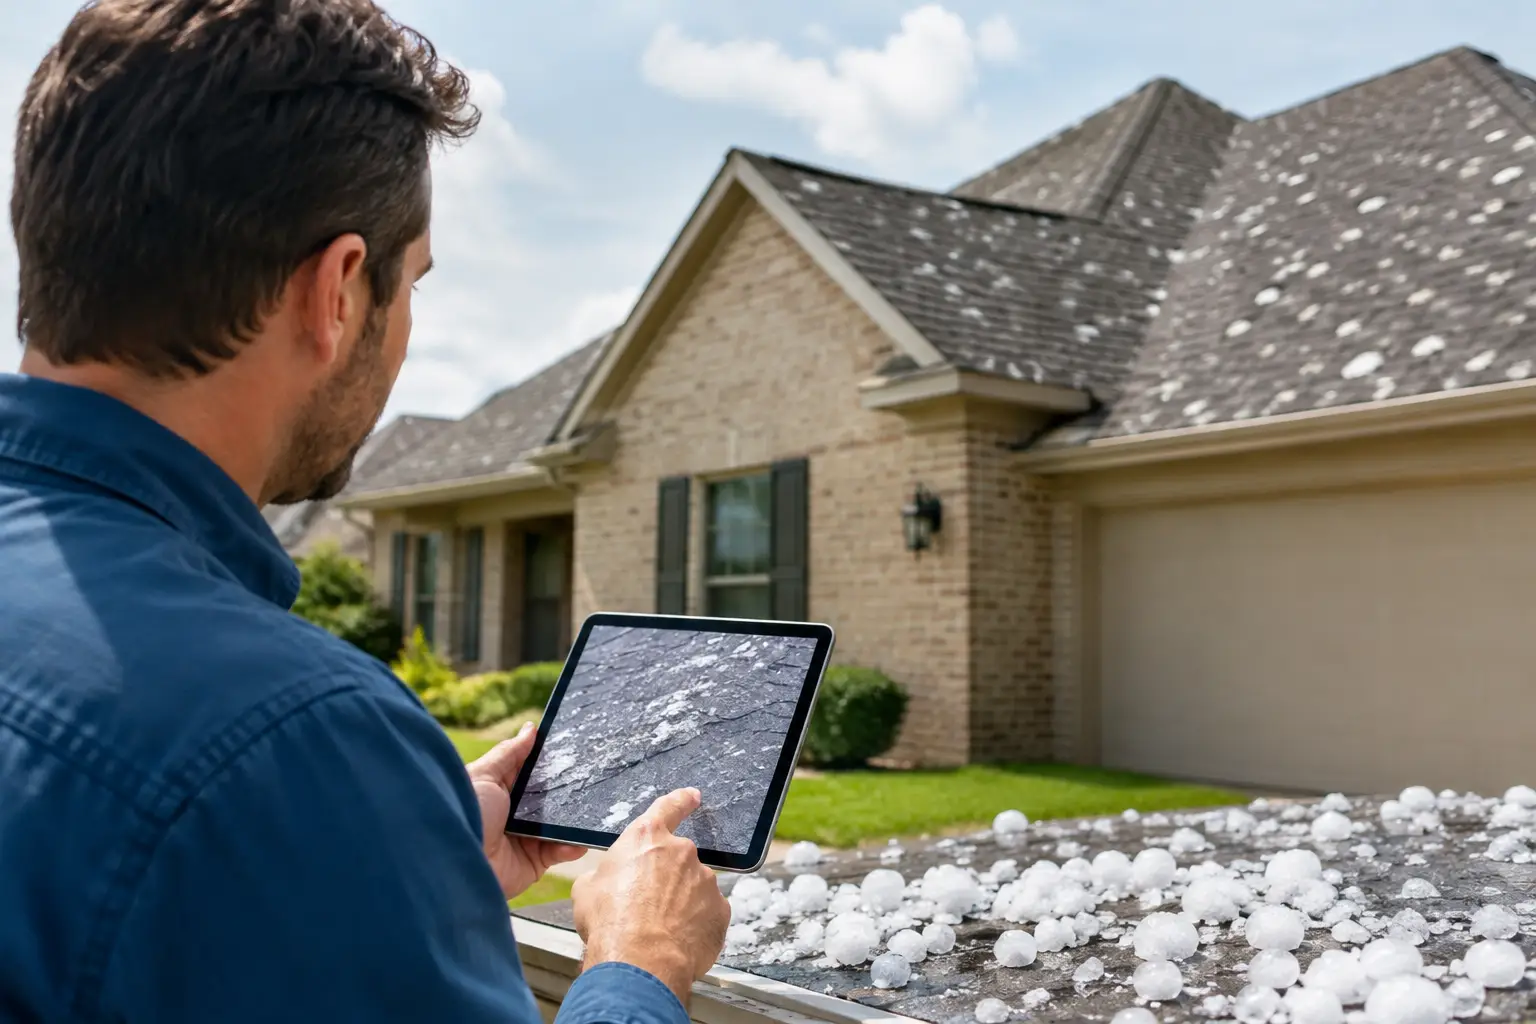
A Texas hail insurance claim example is most useful when it shows more than a damaged roof. The real financial result depends on how the policy was designed before the storm: the roof settlement basis, deductible, applicable exclusions, policy limits, and the documentation supporting the loss. A hailstorm may look like a straightforward event, but the claim is where coverage architecture becomes visible.
Consider a homeowner whose property is struck by a spring hailstorm. The roof, gutters, screens, and several windowpanes show damage. The homeowner reports the loss promptly, but the final payment is not simply the contractor's estimate minus a small fee. Each portion of the policy has a job to do, and each can change the amount the homeowner ultimately receives.
The Texas Hail Insurance Claim Example
Assume the home is insured for $500,000, with a 2% wind and hail deductible. The deductible is therefore $10,000. The policy provides replacement cost coverage for the dwelling, but the roof has a separate settlement provision that pays actual cash value until repairs are completed. That provision is common enough to deserve close attention when a policy is selected or renewed.
After the storm, a qualified inspection identifies the following covered damage:
- Roof replacement estimate: $31,500
- Gutters and downspouts: $2,800
- Window screens and exterior lighting: $1,200
- Interior water staining caused by a hail-damaged roof vent: $2,500
The total covered repair estimate is $38,000. At first glance, a homeowner might expect a $28,000 payment after the $10,000 deductible. That may be close to the final figure, but it is not necessarily the first check.
The carrier's adjuster confirms covered hail damage and agrees on a replacement cost value of $38,000. The estimate includes reasonable material and labor costs, subject to the policy terms. The adjuster then applies the $10,000 wind and hail deductible. If the policy permits recoverable depreciation for the roof and other damaged components, the carrier may also hold back depreciation until repairs are documented.
Suppose the initial depreciation holdback is $6,000. The initial payment would be $22,000: $38,000 in covered damage, less the $10,000 deductible and $6,000 in recoverable depreciation. Once the homeowner completes repairs and submits the final invoice, the additional $6,000 may be released, bringing total insurance payments to $28,000.
The homeowner still bears the $10,000 deductible. That cost is not a billing inconvenience or an amount a contractor should quietly absorb. It is the portion of the loss the policy requires the insured to retain. A percentage deductible can be manageable for one household and a significant financial exposure for another, which is why it should be evaluated against the home's insured value and the owner's available reserves.
Why the First Payment May Not Be the Final Payment
A claim estimate is an assessment based on conditions visible at the time. Roofing materials may be removed later and reveal damaged decking, flashing, or ventilation components that could not be fully evaluated during the first inspection. When additional storm-related damage is discovered, the contractor can provide documentation and the carrier can consider a supplemental claim.
A supplement is not automatic. It should identify newly discovered damage, explain how it relates to the covered event, and support the cost with photographs, measurements, invoices, or other relevant records. It is also not a substitute for broadening the scope beyond what the policy covers.
In this example, removal of the existing roof reveals $3,500 in hail-related damage to flashing and roof decking. The carrier accepts the supplement. Because the deductible was already applied to the original loss, it generally is not applied a second time to the same occurrence. The additional covered amount is paid according to the same replacement cost and depreciation provisions that apply to the rest of the claim.
This is one reason homeowners should not rush from a brief curbside inspection to a repair agreement. A careful inspection, clear records, and a contractor estimate that separates storm damage from maintenance issues create a more reliable claim file.
Where Coverage Can Change the Outcome
The numbers in a Texas hail insurance claim example change materially when the policy has a different roof provision. Replacement cost coverage is designed to help restore covered property with like kind and quality materials, subject to the policy conditions. Actual cash value coverage accounts for age and wear, meaning depreciation may be permanent rather than recoverable.
Take the same $31,500 roof estimate. If the roof is older and settled at actual cash value, the carrier may calculate $18,000 after depreciation. The $10,000 deductible could reduce the roof payment to $8,000, before considering the other covered damage. That is a very different recovery than a replacement cost settlement.
Matching requirements also matter. If hail damages one slope of a roof, the question is not always whether the policy will fund an entirely new roof. The answer can depend on the extent of physical damage, repairability, local requirements, and the policy's provisions for matching materials or appearance. Coverage for cosmetic damage can be limited under some policies, particularly for metal roofs, siding, shutters, or similar exterior finishes.
Policy limits create another boundary. Dwelling coverage should be designed around the estimated cost to rebuild the structure, not its market price or mortgage balance. If the limit is too low, a major storm can expose the owner to costs that insurance was meant to absorb. Separate structures, personal property, and loss-of-use coverage have their own limits and may come into play if hail causes broader damage or makes the home temporarily unlivable.
A Disciplined Response After a Hailstorm
The strongest claim begins with measured action. Photograph damage from a safe location, including hail accumulation, dented metal surfaces, broken windows, and interior water entry. Record the date and approximate time of the storm. Save invoices for reasonable emergency measures, such as tarping an opening to prevent additional rain damage.
Then report the loss promptly and review the policy declarations page before making major decisions. Confirm the deductible type and amount, whether the roof is settled at replacement cost or actual cash value, and whether the policy contains endorsements that affect wind, hail, cosmetic damage, or roof surfaces. A claims conversation is more productive when the homeowner understands the framework of the policy.
Use a qualified professional to inspect the property, but do not sign an agreement that assigns broad control of the claim or commits you to unnecessary work before the scope is understood. Contractors can provide valuable evidence about repair needs and cost. The insurer, however, makes the coverage determination under the policy, and the homeowner remains responsible for informed choices throughout the process.
Keep every estimate, photograph, adjuster report, repair invoice, and communication in one organized file. If the scope differs between the contractor and carrier, identify the specific line items in dispute rather than treating the disagreement as a general complaint. Precision is more effective than frustration.
Design the Protection Before the Storm
Hail is a recurring property risk in many parts of Texas, but a claim should not be the first time a homeowner learns how the policy handles the roof. The right deductible, settlement terms, dwelling limit, and endorsements should fit the property, its materials, and the owner's capacity to absorb an out-of-pocket loss.
A lower premium can sometimes reflect a higher percentage deductible, actual cash value roof terms, or narrower protection for exterior finishes. Those trade-offs may be reasonable, but only when they are intentional. Insurance works best when its structure is understood before weather turns it from a policy document into a financial decision.
A well-designed policy cannot prevent hail from falling. It can give the owner a clearer path to repair, stronger financial footing, and fewer surprises when the roofline tells the story of the storm.